

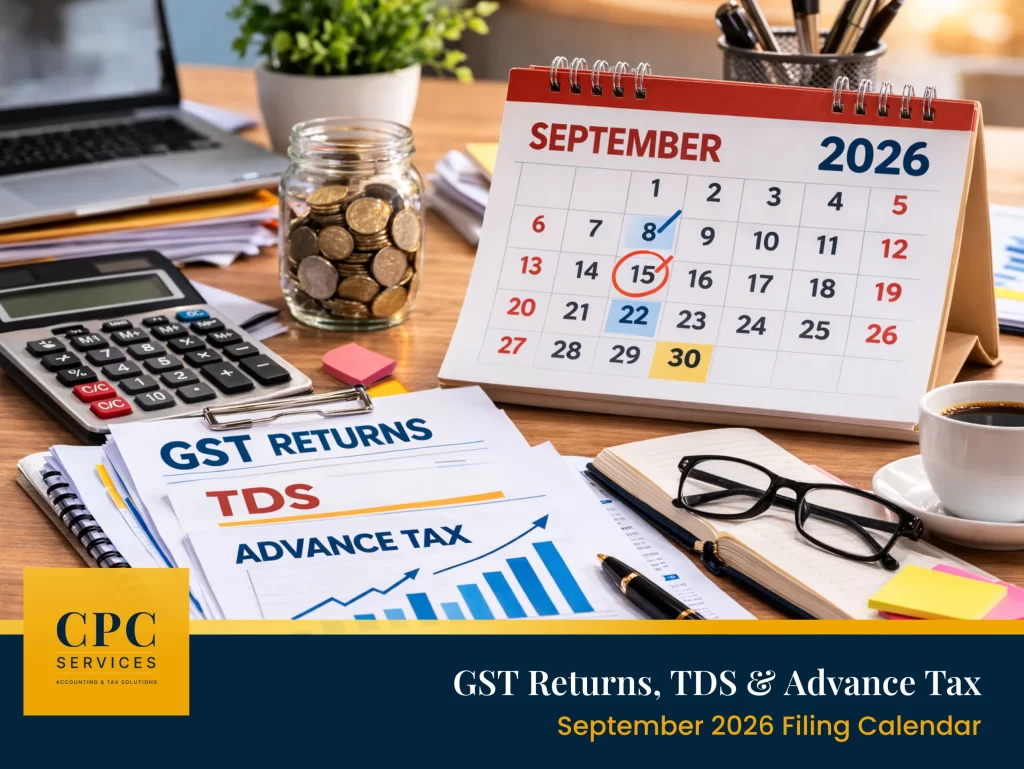
Every deadline your business needs to hit in September 2026 — explained simply, with what each filing involves and exactly what it costs to miss it.
September is the most compliance-intensive month of the financial year for Indian businesses. Three major obligations converge in a single 30-day window: GST return filings for August, the second installment of advance tax for FY 2026-27, and the monthly TDS deposit cycle. Most crucial is furnishing of Audit Report under section 44AB (of Income-tax Act, 1961 as applicable for FY 2025-2026) on or before due date i.e. 30th September 2026. A single day delay may cost a heavy penalty which may extend to 1.50 Lakh.
For businesses with turnover above ₹5 crore, GSTR-3B is due on 20 September. The advance tax second instalment — 45% of estimated annual liability, cumulative — is due on 15 September. The TDS deposit for August deductions is due on 7 September. If your business falls under all three, you have a significant cash flow obligation in a single fortnight.
This blog gives you every deadline for September 2026, explains what each involves, and gives you the penalty calculation for any you miss — so you can prioritize correctly and avoid paying a rupee more than you owe.
KEY TAKEAWAY
September 2026 is critical for two key reasons. 15 September is the second advance tax instalment, requiring cumulative payment of 45% of estimated annual tax, with interest implications for shortfalls. The FY 2025–26 ITC final window also closes this month, so eligible unclaimed ITC must be claimed in the September GSTR-3B before the deadline.
Finally, Q2 closes on 30 September. QRMP taxpayers will file their quarterly GSTR-3B in October, but businesses should complete their books reconciliation, ITC matching, and supplier follow-ups before 30 September to stay prepared.
All September 2026 Compliance Deadlines at a Glance
This is your complete compliance calendar for September 2026. Dates shaded in blue are GST deadlines; those in green are income tax and TDS deadlines.
| Type | Due Date | Form / Filing | Who It Applies To | Cost of Missing It |
| INCOME TAX & TDS | 7 Sep 2026 | TDS Deposit | All non-government deductors: deposit TDS deducted in August 2026 | 1.5%/month interest from deduction date + 30% expense disallowance risk |
| INCOME TAX & TDS | 7 Sep 2026 | TCS Deposit | E-commerce operators and notified TCS collectors: deposit TCS for August 2026 | Same interest and disallowance as TDS |
| INCOME TAX & TDS | 15 Sep 2026 | Advance Tax Q2 | All taxpayers with estimated tax liability above ₹10,000 after TDS: pay 45% of annual tax (cumulative) | 1% per month under Section 234C on shortfall from both June and September instalments |
| INCOME TAX & TDS | 30 Sep 2026 | Tax Audit Report | Businesses and professionals requiring tax audit: CA must sign and upload Form 3CD on portal | ITR deadline of 31 October 2026 depends on audit report by 30 September — delays cascade |
| GST | 10 Sep 2026 | GSTR-7 | Government bodies and notified entities deducting TDS under GST: monthly return for August 2026 | ₹50/day late fee + blocks deductee’s GST TDS credit |
| GST | 10 Sep 2026 | GSTR-8 | E-commerce operators collecting TCS under GST: monthly return for August 2026 | ₹50/day late fee + deductee cannot claim TCS credit |
| GST | 11 Sep 2026 | GSTR-1 | Monthly filers (turnover >₹5 Cr or opted monthly): outward supply return for August 2026 | ₹50/day late fee; buyer ITC blocked; hard-locked GSTR-3B cannot compensate |
| GST | 13 Sep 2026 | GSTR-5 | Non-resident taxable persons: GST return for August 2026 | ₹50/day late fee; registration may be cancelled for repeated defaults |
| GST | 13 Sep 2026 | GSTR-6 | Input Service Distributors: ISD return for August 2026 | ₹50/day late fee; ITC distribution to branches delayed |
| GST | 20 Sep 2026 | GSTR-3B | Monthly filers (turnover >₹5 Cr): summary return + tax payment for August 2026 | ₹50/day late fee + 18% p.a. interest on unpaid tax from 20 Sep |
| GST | 25 Sep 2026 | PMT-06 | QRMP taxpayers: monthly GST tax payment for August 2026 | 18% p.a. interest on late payment; quarterly GSTR-3B filing will reflect deficit |
| GST | 30 Sep 2026 | GSTR-2B Reconciliation | All registered taxpayers: deadline to complete FY 2025-26 ITC reconciliation before Q2 close | FY 2025-26 ITC lapses after October 2026 GSTR-3B due date — credit permanently lost |
QUICK TIP
Not sure if advance tax applies to you? It does if your estimated income tax liability for FY 2026-27 exceeds ₹10,000 after accounting for TDS already deducted from salary, bank interest, contractor payments, etc. If you are salaried and your employer deducts full TDS, you may still owe advance tax if you have rental income, capital gains, FD interest, or any income not covered by employer TDS.
TDS Compliance in September 2026
TDS Deposit — 7 September 2026
Any TDS deducted from payments made in August 2026 must be deposited with the government by 7 September 2026. This applies to salary TDS (deducted monthly from employee salaries), TDS on contractor payments, professional fees, rent, interest, commission, and any other payment where TDS is applicable under the Income Tax Act, 2025.
Governing law: Since all August 2026 payments occur after 1 April 2026, TDS is now governed by Section 393 of the Income Tax Act, 2025 (not Sections 194C, 194J, 194H etc. of the old Act). When depositing TDS, ensure your challan quotes the correct new section reference. Portal validation may fail if old Act section numbers are used for post-March 2026 transactions.
IMPORTANT WARNING
Two separate penalty streams apply for TDS default:
Interest: 1.5% per month from date of deduction to date of deposit. Part of a month counts as a full month. A deposit made on 20 September instead of 7 September = 1 full month’s interest (not 13 days).
Expense disallowance: 30% of the amount paid to any resident (on which TDS was deductible but not deposited by ITR filing deadline) will be disallowed as a business expense under Section 35(b) of the Income Tax Act, 2025. This can significantly increase your taxable income.
Advance Tax: The 15 September Deadline Explained
The 15 September deadline is the second of four advance tax installments for FY 2026-27. It is also the most misunderstood — because the percentage required is cumulative, not just for the quarter.
| Instalment | Due Date | Cumulative % Required | If Missed |
| 1st Instalment | 15 June 2026 | At least 15% of annual tax | 1% per month interest under Section 234C on shortfall |
| 2nd Instalment | 15 September 2026 | At least 45% of annual tax (cumulative) | 1% per month on cumulative shortfall from June + September |
| 3rd Instalment | 15 December 2026 | At least 75% of annual tax (cumulative) | 1% per month on cumulative shortfall from all three |
| 4th Instalment | 15 March 2027 | 100% of annual tax (cumulative) | 1% per month under Section 234B on total shortfall if <90% paid |
What ‘cumulative 45%’ means in practice: If your estimated annual tax liability is ₹3 lakh, you must have paid a total of ₹1,35,000 by 15 September — including whatever you paid on 15 June. If you paid ₹30,000 in June (10% — below the required 15%), you need to pay at least ₹1,05,000 in September to reach the 45% cumulative threshold. The shortfall from June also attracts interest.
Who is exempt from advance tax:
- Senior citizens (above 60 years) with no business or professional income — fully exempt from advance tax
- Presumptive taxation taxpayers under Section 44AD and 44ADA (small businesses and professionals with turnover/receipts below the prescribed limits) — can pay 100% of advance tax as a single instalment by 15 March 2027
- Salaried individuals whose entire tax liability is covered by employer TDS — no advance tax required
CPC INSIGHT
The most common advance tax error CPC Services corrects for SME clients is underestimation. Business owners estimate their Q2 advance tax based on Q1 actual — without factoring in a large order they have just won, a property sale completed in August, or capital gains from a mutual fund redemption. If your income in Q2 was materially higher than Q1, revise your advance tax estimate before 15 September — overpaying is free; underpaying costs 1% per month.
→ Explore Financial Advisory Services | Talk to CPC Services
GST Filing Deadlines in September 2026
GSTR-1: Outward Supply Return — 11 September 2026
Monthly GST filers must report all B2B and B2C invoices issued in August 2026 by 11 September. With GSTR-3B hard-locked since July 2025, GSTR-1 accuracy is more important than ever — errors cannot be corrected directly in GSTR-3B and must go through GSTR-1A before GSTR-3B is filed.
- Critical for September specifically: Any FY 2025-26 invoice that has not yet been reported or was reported with errors must be amended in September’s GSTR-1 (Table 9A). The November 2025 amendment cut-off has passed — September is the last practical window to capture FY 2025-26 output corrections before year-end.
- QRMP filers: September is the last month of Q2 (July–September). Your quarterly GSTR-1 for Q2 is not due until 13 October 2026. However, if you have B2B buyers whose ITC depends on seeing your August invoices in their September GSTR-2B, use the Invoice Furnishing Facility (IFF) before 13 September to upload those invoices for the month.
GSTR-3B: Summary Return + Tax Payment — 20 September 2026
GSTR-3B for August 2026 is due 20 September for monthly filers. This is simultaneously the most important deadline this month and the one with the most cash flow impact — particularly for businesses that also owe advance tax by 15 September.
- September-specific cash flow alert: If you owe both advance tax (15 Sep) and GSTR-3B tax payment (20 Sep), plan your liquidity carefully. Both are cash outflows within 5 days of each other. For a business with ₹50 lakh monthly GST turnover, the GSTR-3B net tax payment alone can be ₹3–8 lakh. Add the advance tax instalment and the combined cash requirement in one fortnight is material.
REMINDER
September GSTR-3B is the final return for FY 2025-26 ITC claims. Any input tax credit from FY 2025-26 (April 2025–March 2026) that has not yet been claimed must be included in this return. After the 20 October 2026 due date for September GSTR-3B, unclaimed FY 2025-26 ITC lapses permanently. There are no extensions for this deadline.
PMT-06: Monthly GST Payment for QRMP Taxpayers — 25 September 2026
QRMP taxpayers file GST returns quarterly but pay tax monthly. The August 2026 tax payment via Form PMT-06 is due by 25 September. The amount can be calculated using either the Fixed Sum Method (35% of previous quarter’s GSTR-3B tax) or the Self-Assessment Method (based on actual August ITC and liability). If August was a high-revenue month compared to last quarter, the Fixed Sum Method may underpay — use the Self-Assessment Method for accuracy.
Tax Audit Report Deadline — 30 September 2026
Businesses and professionals whose books are required to be audited under Section 44AB must have their Chartered Accountant sign and upload the tax audit report (Form 3CD/3CA/3CB) by 30 September 2026. The ITR filing deadline for audit cases is 31 October 2026 — which is directly dependent on the audit report being completed first.
Who this applies to:
Businesses with turnover above ₹1 crore (₹10 crore if cash transactions are below 5%), and professionals with gross receipts above ₹50 lakh (₹75 lakh under presumptive scheme). Directors of private limited companies and partners of auditable firms also need to ensure the entity-level audit is complete before their personal ITR deadline.
ADVISORY
Audit and ITR are separate obligations but one blocks the other. If your CA has not completed the tax audit report by 30 September, your ITR cannot be filed by 31 October. A late ITR for audit cases attracts ₹5,000 late fee and more significantly — blocks the ability to choose the old tax regime (the new regime becomes the default for belated returns). Start the audit preparation now, not in the last week.
→ Explore Audit & Assurance Services | Explore Direct Tax Advisory
What Each Missed Deadline Costs You: September Edition
September’s deadlines are more expensive to miss than most months — because three of them carry compounding consequences.
| Deadline | Late Fee | Interest | Hidden Cost |
| TDS Deposit (7 Sep) | None on deposit | 1.5%/month from deduction date | 30% expense disallowance if not deposited by ITR date |
| Advance Tax (15 Sep) | None | 1% per month on shortfall under Section 234C | Shortfall from June instalment also starts attracting interest — compounding from both quarters |
| GSTR-1 (11 Sep) | ₹50/day, no cap stated | None on GSTR-1 directly | Buyer’s GSTR-2B blocked → their ITC impacted → they chase you → relationship risk |
| GSTR-3B (20 Sep) | ₹50/day, capped ₹5,000 | 18% p.a. on unpaid tax from 20 Sep | Final FY 2025-26 ITC lapse — unclaimed credit permanently lost |
| PMT-06 (25 Sep) | None on payment | 18% p.a. from 25 Sep on deficit | Quarterly GSTR-3B will show underpayment and attract further interest |
| Tax Audit (30 Sep) | 0.5% of the turnover or Rs.1.50 Lakh which-ever is lower. | N/A | Failed to Furnish the report, Likely to miss ITR deadline → ₹5,000 late fee + old regime option lost + reputation risk with lenders |
Planning Your September Cash Flow: The Fortnight That Matters
For any SME owner juggling GST, TDS, and advance tax simultaneously, September requires deliberate cash flow planning. Here is the sequence of outflows and what to prepare:
| Date | Obligation | Cash Flow Planning Action |
| 7 Sep | TDS deposit for August 2026 | Calculate total TDS deducted in August across all categories. Ensure bank balance covers this before the 7th. Late TDS deposit is one of the most common inadvertent defaults. |
| 11 Sep | GSTR-1 for August 2026 | No cash outflow — but file accurately. Errors here cannot be corrected in GSTR-3B. Review all B2B invoices, credit notes, and advances before submission. |
| 15 Sep | Advance tax Q2 instalment (45% cumulative) | Calculate estimated annual tax, subtract June payment and TDS credits. Pay the balance due to reach 45% cumulative. Use Challan 280 online — select Tax Year 2026-27 and Minor Head 100 (Advance Tax). |
| 20 Sep | GSTR-3B for August 2026 — final FY 2025-26 ITC date | Reconcile with GSTR-2B before filing. Claim all remaining FY 2025-26 ITC in this return. After 20 Oct deadline, any unclaimed credit is lost. Pay net GST due before filing. |
| 25 Sep | PMT-06 for August 2026 (QRMP taxpayers only) | Calculate using Self-Assessment Method if August sales were significantly higher than last quarter. Fixed Sum Method may underpay. |
| 30 Sep | Tax audit report due; Q2 books reconciliation close | Coordinate with your CA for timely audit completion. Finalise Q2 GST-books reconciliation. Last day for QRMP filers to resolve pending FY 2025-26 ITC issues before Q2 closes. |
CPC INSIGHT
CPC Services builds a monthly cash flow projection for each client’s compliance obligations — mapping TDS, GST, advance tax, and professional fee outflows against expected receivables. For September, this single document typically saves SME clients from inadvertent late payments caused by cash being tied up in receivables when a compliance due date arrives.
→ Explore Accounting & Virtual CFO Services | Visit the Compliance Desk
September Has Three Deadlines in One Fortnight. Let’s Make Sure You Hit All of Them.
Related Reading
→ July 2026 GST & TDS Due Dates: Don’t Miss These Compliance Deadlines
→ Advance Tax September 15 Deadline: How to Calculate & Pay Correctly
→ Quarterly Review: How to Reconcile GST & Books Before Q2 Ends
→ 10 Signs Your Growing Business Needs a Virtual CFO Right Now

